Moving Insurance Explained: Released Value vs Full Value Protection
Quick answer: "Moving insurance" usually means one of two things: the valuation in your moving contract or a separate third-party policy. Released value, the basic valuation, limits a mover's liability to 60 cents per pound per article, so a 10-pound, $1,000 item pays about $6. On interstate household-goods moves, federal rules require movers to offer Full Value Protection too (repair, replace or pay for the item), and it applies unless you waive it in writing.
Key takeaways
- "Valuation" is the mover's liability for your goods under your contract. Third-party moving insurance is a separate policy from an insurer.
- Released value pays by weight, not value: light, expensive items get very little.
- For interstate household-goods moves, movers must offer Full Value Protection, and choosing released value instead requires your written, signed statement.
- Inspect on delivery, note damage in writing, and file interstate claims within 9 months.
The valuation option on your paperwork decides whether a damaged $1,000 item pays $1,000 or $6.
The sections below cover what each option pays, how third-party insurance differs, which rules apply to which moves, and how to file a claim. The federal rules described here apply to interstate household-goods moves; other moves may follow state rules or the terms of your contract.
What is moving valuation, and is it the same as insurance?
No. Valuation is the level of liability your mover accepts for your belongings while they are in its care, and it is set out in your moving contract. Moving insurance is a separate policy sold by an insurance company. FMCSA also distinguishes valuation from the mover's own business insurance, which covers the company's facilities, equipment, vehicles and employees rather than your belongings. For interstate household-goods moves, FMCSA says movers must offer two valuation levels: Full Value Protection and Released Value.
Released value protection: the 60-cents-per-pound option
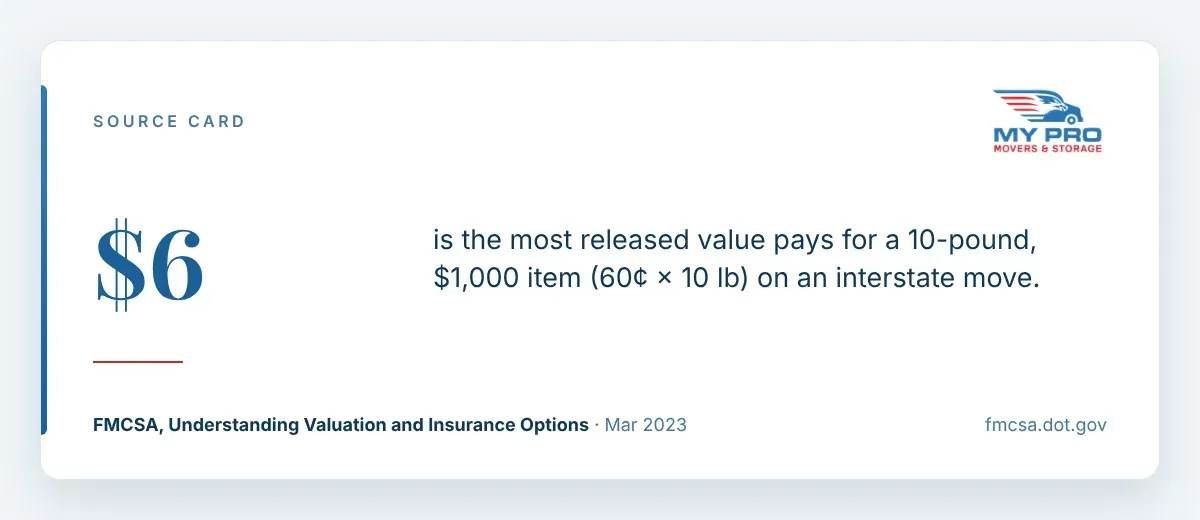
Released value is the no-extra-cost option, and that is its main appeal. But it pays by weight, not by what an item is worth. According to FMCSA, the mover is liable for "no more than 60 cents per pound per article," and you must sign a statement on the bill of lading or contract to choose it. FMCSA's own example: a 10-pound stereo component worth $1,000 would pay $6.00 (60 cents × 10 pounds). Under 49 CFR 375.201, the released rate is set by a Surface Transportation Board order and carriers may adjust it annually, so confirm the exact rate in your contract.
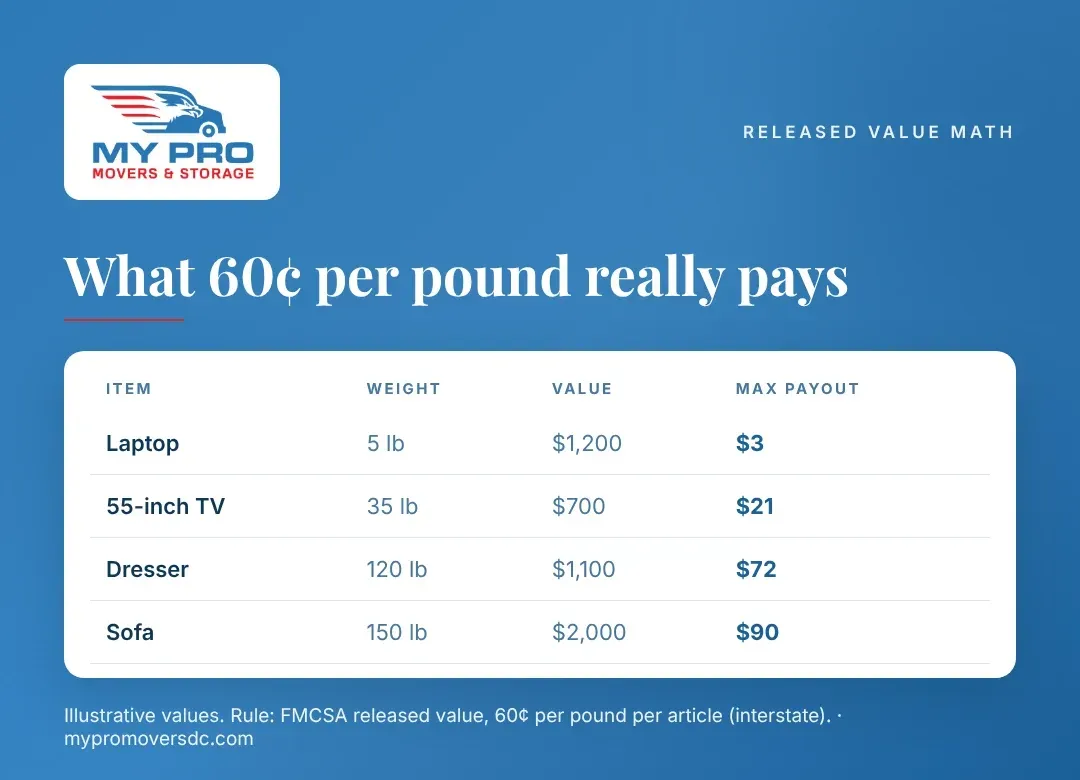
| Item (illustrative) | Weight | Value | Max payout at 60¢/lb |
|---|---|---|---|
| Laptop | 5 lb | $1,200 | $3 |
| 55-inch TV | 35 lb | $700 | $21 |
| Dresser | 120 lb | $1,100 | $72 |
| Sofa | 150 lb | $2,000 | $90 |
Released value can make sense if most of what you're moving is heavy and inexpensive, or if you're moving a few items you could replace cheaply. For anything light and valuable, it's close to no coverage at all.
Full Value Protection: what it covers
Under Full Value Protection (FVP), the mover is responsible for the replacement value of lost or damaged goods in the entire shipment, up to the declared value of the shipment (49 CFR 375.201). For each damaged or lost item, the mover may repair it, pay for the repair, replace it with a similar item, or pay a cash settlement. FMCSA says your shipment moves under FVP unless you choose released value in writing. FMCSA's handbook sets the minimum value for FVP at $6.00 per pound times the weight of your shipment; movers may set a higher minimum, and you can declare a higher value for an additional cost.
Deductibles and cost
FVP costs more than released value, and the price varies by mover. Some movers offer deductible levels that lower the cost: you pay the first part of a claim, the mover covers the rest. Ask for the price, deductible and terms in writing before you sign.
High-value items: the $100-per-pound rule
Under FVP, a mover may limit its liability for "articles of extraordinary value." FMCSA's handbook defines these as items worth more than $100 per pound, such as jewelry, silverware, china, furs or antiques, unless you list them on the shipping documents. List them in writing before the move, or carry small valuables yourself.
Released value vs full value protection at a glance
| Released value | Full Value Protection | |
|---|---|---|
| Cost | No extra charge | Extra charge; varies by mover |
| What the mover pays | Up to 60¢ per pound per item | Repair, replace, or current market replacement value |
| Example: 10-lb, $1,000 item | About $6 | Repair, replacement or up to its value (less any deductible) |
| How you choose it | Sign a statement on the bill of lading or contract | Applies unless you waive it in writing (interstate) |
| High-value items | Same 60¢/lb limit | List items over $100/lb in writing |
| Best for | Heavy, inexpensive items | Light or fragile valuables, electronics, newer furniture |
Does homeowners or renters insurance cover a move?
Sometimes, partly. FMCSA suggests checking whether your homeowner's policy already covers your belongings before you buy extra coverage. Policies differ: some cover goods in transit only for named events, such as a fire or a truck accident, and some do not cover them at all. Call your insurer before moving day and ask three things: are my belongings covered in transit, at what limit, and for which events?
Third-party moving insurance is a separate policy from an insurance company. It is bought in addition to the mover's valuation, and claims follow the policy's terms. FMCSA says a mover may, but is not required to, offer to sell you separate liability insurance; if you buy it from or through the mover, you should receive the policy or written evidence of it. Disputes with a third-party insurer are not covered by FMCSA regulations. Before you buy coverage, verify the mover's registration and insurance on FMCSA.
Which rules apply to your move?
FMCSA's household-goods rules (49 CFR part 375) apply to household goods motor carriers moving goods for individual shippers by motor vehicle in interstate commerce. FMCSA's handbook says they do not apply to moves within a commercial zone or between two points in the same state. Whether a short move across the DC, Maryland or Virginia line counts as interstate, or falls within a commercial zone, depends on the facts, so ask your mover which rules apply to your move and get the answer in writing. For moves within one state, FMCSA says each state may have its own rules; your state consumer agency or moving association can tell you what applies.
Example: one damaged TV, two possible payouts
This example is illustrative and assumes an interstate move under FMCSA rules. A 35-pound, $700 TV is damaged beyond repair.
- Released value: 35 lb × $0.60 = $21 .
- Full Value Protection with no deductible: the mover repairs or replaces the TV, or pays its current market replacement value.
- Full Value Protection with a deductible: the same, minus the deductible the family agreed to.
The coverage choice was one line on the paperwork, made before the move.
How to choose the right coverage: 5 questions
- What would it cost to replace my five most valuable items, and how much do they weigh?
- Does my homeowners or renters policy cover goods in transit, and up to what limit?
- What does Full Value Protection cost from this mover, and at which deductible levels?
- Do I have items over $100 per pound that I need to list in writing?
- Is my move interstate (federal rules) or in-state (state rules and my contract)?
Questions about coverage for your move?. Tell us about your move and ask how valuation and third-party insurance would work for it. Get my free moving quote
How to file a moving damage claim
- Inspect on delivery. Open boxes with fragile items and check furniture before the crew leaves.
- Write it down. Note visible damage or missing items on the inventory or delivery receipt before signing, and do not sign a delivery receipt that releases the mover from liability.
- Take photos of damaged items and packaging, and keep the boxes.
- File in writing. For interstate moves you have 9 months from delivery (FMCSA). The mover must acknowledge your claim within 30 days and give a disposition within 120 days, with possible 60-day extensions if it notifies you in writing (FMCSA handbook). For other moves, check your contract and state rules.
- Use dispute resolution if needed. Interstate household-goods movers must take part in a dispute settlement program and give you a summary on request.
Coverage warning signs
- "You're fully covered" with nothing in writing. Ask which valuation level you are choosing and what it pays.
- Pressure to sign a released-value waiver without an explanation of what it pays. More warning signs are in 12 moving scam red flags.
- No clear answer about which company is the carrier responsible for damage and who handles claims.
- Blank fields on the bill of lading, or a delivery receipt that releases the mover from liability.
How MyProMovers handles coverage
Our standard valuation is $0.60 per pound per article, included at no extra cost. It is not full-value coverage: it pays by weight, not replacement cost. For any other coverage option, please review the written coverage options in your contract or ask your MyProMovers representative before you book. Third-party moving insurance is a separate policy from an insurer, and the choice is yours.
- Certificate of insurance (COI): a separate document that some buildings require. We send ours free of charge; each additional insured is $150. It is separate from valuation.
- About MyProMovers: USDOT #3116640, MC #1001869, Virginia Intrastate For-Hire Certificate #709; 40,000+ completed moves.
Frequently asked questions about moving coverage
What is the difference between released value and full value protection?
Released value is no-extra-cost coverage that pays no more than 60 cents per pound per article. Full Value Protection costs extra and makes the mover responsible for the replacement value of lost or damaged goods (repair, replace or cash settlement). On interstate household-goods moves, movers must offer both, and FMCSA says shipments move under FVP unless you choose released value in writing.
What does 60 cents per pound mean?
It means the mover's maximum liability for a lost or damaged item is 60 cents multiplied by its weight in pounds, regardless of its value. A 10-pound, $1,000 item would pay about $6; a 35-pound TV about $21. This is the released value option under federal rules for interstate moves.
Is full value protection worth it?
It depends on what you are moving. Compare what released value would pay for your most valuable items (by weight) with the price and deductible options for Full Value Protection. It matters most for light, valuable items such as electronics. Ask for the price and terms in writing.
Does homeowners insurance cover moving?
Sometimes, but often only partly. Policies differ: some cover goods in transit only for named events, such as a fire or a truck accident, and some do not cover them at all. Call your insurer before moving day to confirm whether goods in transit are covered, the limit and which events apply.
How long do I have to file a moving claim?
For interstate moves, you have 9 months from the delivery date to file a written claim. The mover must acknowledge it within 30 days and give a disposition within 120 days. For moves within one state, check your contract and state rules.
Do I need moving insurance?
Not always. Your moving contract sets the mover's valuation, which is what the mover pays for loss or damage; the basic released value pays only 60 cents per pound per article. Check what that would pay for your most valuable items and whether your homeowners or renters policy covers goods in transit. If neither covers what you could lose, ask the mover about Full Value Protection or buy third-party moving insurance before moving day.
Is valuation the same as moving insurance?
No. Valuation is the mover's liability under your moving contract. Third-party moving insurance is a separate policy from an insurance company, and disputes with a third-party insurer are not covered by FMCSA regulations. Check what the policy covers before you rely on it.
The bottom line
Released value costs nothing because it pays very little: 60 cents per pound will not replace a laptop, a TV or a favorite chair. On interstate household-goods moves, Full Value Protection is the option that makes the mover responsible for replacement value. Check your home policy, list your valuables, and get your coverage choice in writing.
Questions about coverage for your move?. Tell us about your move and ask how valuation and third-party insurance would work for it. Get my free moving quote
Related guides
Sources
- FMCSA, Protect Your Move: "Liability & Protection", accessed Nov 2026.
- FMCSA, "Understanding Valuation and Insurance Options" (PDF), Mar 2023.
- FMCSA, "Your Rights and Responsibilities When You Move" (consumer handbook), Oct 2023 edition (current).
- eCFR, 49 CFR Part 375 (§§375.101, 375.201, 375.203), accessed Nov 2026.